

Everywhere I look online, people are focused on income. Wall Street knows this and a whole slew of income ETFs have now launched.
Many of these funds are covered call strategies. Fundamentally, covered calls generate premium through selling the potential upside on a holding.
Essentially, someone is saying, “Rather than take the chance of watching this stock go up, I’d like to be paid today and if it goes up, I won’t participate in that upside.”
Over long periods of time, we can see that selling the potential upside of equities may have adverse impacts on one’s portfolio.
But alas, the people love the idea of income. Distributions from these funds can receive different tax treatments, including ordinary income, capital gains, or return of capital. Return of capital generally isn’t immediately taxable, instead reducing an investor’s cost basis. This can effectively defer taxation.
I think young folks (or anyone for that matter) should focus on total return for their goals. The number one thing I am concerned with in my own portfolio is the total return after taxes.
But these folks on X just keep shilling and what really grinds my gears is the comparisons they give you.
Essentially, I keep running into posts like this one below.
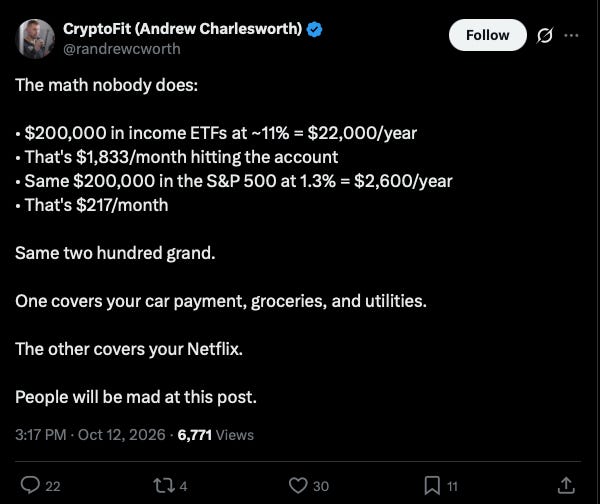
It drives me absolutely nuts. Sometimes when people see a terrible comparison, they’ll say, “This is like comparing apples to oranges.” But the post above is like comparing a tortoise to a Ferrari. It’s just not a fair comparison.
Sure, the income distributed from the funds may be much different, but failing to acknowledge the strategy of an income fund versus an index that would be more focused on capital appreciation is so silly. Additionally, an 11% distribution does NOT mean the fund generates an 11 return%!!! The fund can literally just return some of the capital contributed.
Total return is what I am concerned with. Also, in the event the distributions from the income fund are ROC or return of capital in excess of what the fund generated for investors, the fund is literally just distributing back the money someone put in.
That’s ironic to me. Just so everyone knows, anyone can create income from a portfolio through this magical thing called selling. However, selling allows YOU to choose when you wish to realize taxes and you can defer the taxes until you choose to sell.
Young folks have more access than ever to incredible financial education online, but we are also bombarded with absolutely asinine takes that can just be outright misleading.
It has never ever been more important to vet your sources.
This is for informational purposes only and is not intended as legal, tax, or investment advice or a recommendation of any particular security or strategy. The investment strategy and themes discussed herein may be unsuitable for investors depending on their specific investment objectives and financial situation. Opinions expressed in this commentary reflect subjective judgments of the author based on conditions at the time of publication and are subject to change without notice. Past performance is not indicative of future results.